Sah savings sukuk: eligibility, returns and early redemption
Ali Almesfer · Reviewed 13 October 2026
Sah is a Saudi government savings sukuk product for Saudi citizens aged over 18. The minimum subscription is SAR 1,000 through a participating financial institution. Each issue has its own return and subscription window. Sah is held to a one-year maturity or redeemed in published windows, with accrued profit forfeited on early withdrawal.
The National Debt Management Center (NDMC) publishes the live Sah calendar, participating institutions and issue terms. A rate quoted for a past issue is not the rate for a new subscription. Read the current issue before committing cash.
Sah is registered but is not bought or sold on the Saudi Exchange. It has different access and exit rules from listed sukuk, REIT units or an ordinary bank savings account.
Who can subscribe and how much?
Condition
Current NDMC description
What to check
Eligible subscriber
Saudi citizen older than 18
Nationality and age eligibility; Saudi residence alone is insufficient.
Participating institution
An account with one of the institutions shown by NDMC
Your provider's current Sah subscription route.
Minimum
SAR 1,000, the nominal value of one sukuk
Available cash during the issue's subscription period.
Programme maximum
SAR 200,000 per person across programme issues
Your existing holdings and remaining capacity.
The NDMC currently lists participating institutions on the Sah portal. Check that live list; a different brokerage account or a non-Saudi passport does not create eligibility.
How a Sah subscription works
Open the NDMC Sah calendar and select the current or next issue. Note its subscription dates, announced return and maturity terms.
Use a participating financial institution where you hold an eligible account. Follow that institution's Sah order journey rather than looking for a Tadawul trading symbol.
Check the number of SAR 1,000 sukuk, the total subscription and your remaining programme limit before confirming.
Save the subscription receipt and the issue terms. Check the allocation and holding details in the institution's account.
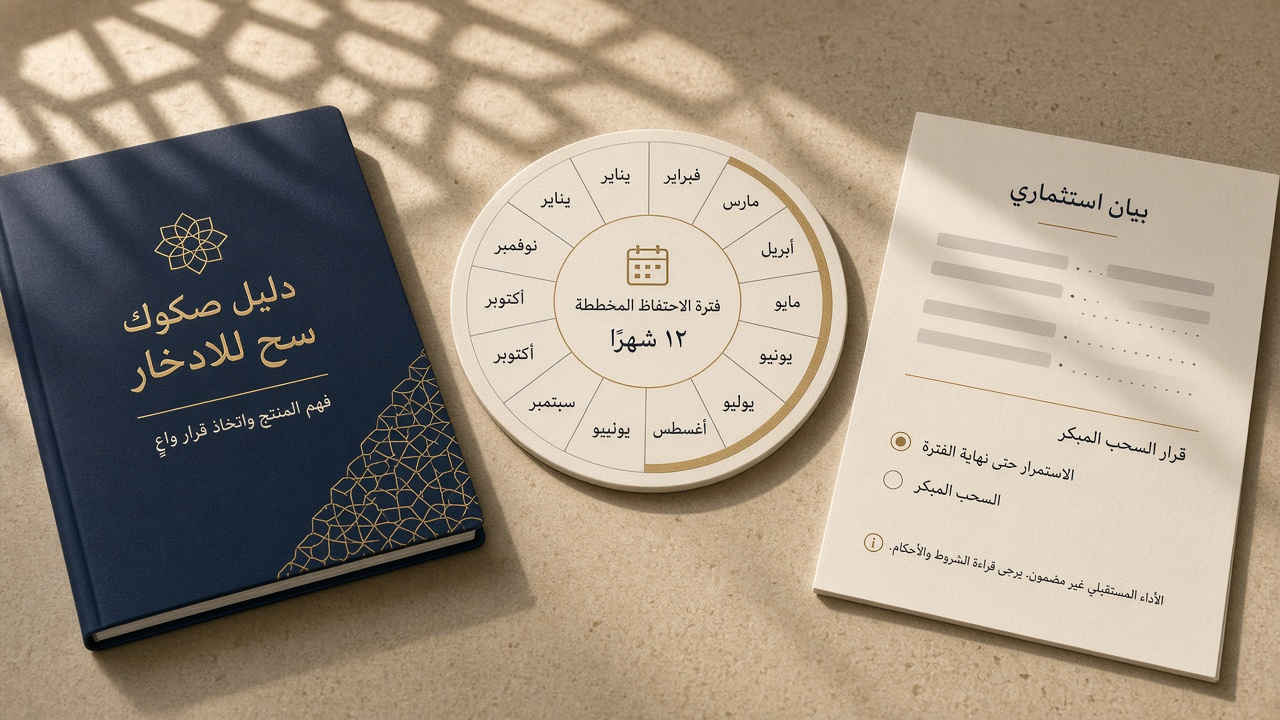
Calendar the one-year maturity and the permitted early-redemption windows if you may need the cash sooner.
The NDMC says Sah has no subscriber fee. Confirm any separate account terms with your participating institution and verify the current calendar rather than assuming continuous subscription.
How is the return calculated and paid?
The return is fixed for each issue but may differ between monthly issues. NDMC says profit is paid at the one-year maturity. It also states that the product is Shariah-compliant; this guide reports the issuer's description and does not provide an independent religious ruling.
For illustration only, one SAR 1,000 sukuk at a hypothetical annual return of 4% would generate SAR 40 profit at maturity, making SAR 1,040 in principal and profit if held for the full term. This is not an NDMC offer or a current issue rate. Read the actual rate and conditions in the live announcement.
What happens if you need the money early?
Sah is not traded on the exchange. NDMC allows holders to request early redemption only in periods specified by its annual calendar. It says accrued profit is not earned when a holder exits early. The ability to redeem in a window therefore differs from daily access to a bank balance.
Before subscribing, decide whether you can leave the amount for a full year. If you might need it sooner, compare the loss of accrued Sah profit on early redemption with the access terms of other savings products. Keep a separate cash reserve for near-term needs.
Using the hypothetical SAR 1,000 issue at 4% above, an investor who redeems early under the published rules would forgo the illustrative SAR 40 full-term profit; it would be misleading to treat a few months of accrued return as withdrawable cash. Check the live redemption window and the participating institution's processing deadline before relying on a particular cash-availability date.
Sah versus listed sukuk and a savings account
Product
How you enter or exit
Main question
Sah
Subscribe via a participating institution; hold to maturity or use a published redemption window.
Am I eligible, and can I leave the money for one year?
Exchange-listed sukuk
Buy or sell through an eligible market member at an available market price.
What are the issuer, price, liquidity and maturity terms?
Bank savings account
Deposit and withdraw under the bank's account agreement.
What access, rate and account conditions apply?
These routes have different risks and legal terms. A government issuer does not make every savings or sukuk product identical. Compare the exact contract and your need for liquidity.
Read a Sah issue calendar in four stages
Before subscription, identify the live issue, eligibility terms, participating institutions, announced return and the window's opening and closing dates.
During subscription, check the number of SAR 1,000 sukuk ordered, the cumulative programme limit and the institution's confirmation deadline.
After allocation, save the issue identifier, actual holding, maturity date and profit terms shown in your institution's account.
Before maturity, check whether you still need the cash early. If so, find the next published redemption window and the institution's processing cut-off; otherwise check the stated maturity payment route.
A calendar is more useful than an old article quoting last month's return. The issue rate is fixed for that issue, but the next issue may carry a different rate and different dates. Reopen the NDMC portal each time you consider subscribing.
Model the cash you can actually use
Hypothetical path
Illustrative cash result
Important condition
One SAR 1,000 sukuk held one year at 4%
SAR 1,040 principal plus profit
Only if the actual issue has that rate and is held to maturity
Five of the same hypothetical sukuk held to maturity
SAR 5,200 on a SAR 5,000 subscription
Still subject to that issue's actual terms
One sukuk redeemed early in an allowed window
SAR 1,000 principal in this simplified example; no accrued profit
Timing depends on the published window and institution processing
The 4% rate and all cash figures are invented examples, not a current offer. They make the liquidity trade-off visible: a quoted annual return is useful only if you can keep the subscription for the full term. Confirm the redemption terms and payment details of the specific issue.
Three questions before committing savings
First, is the subscriber eligible under NDMC's nationality, age and participating-institution conditions? A Saudi address or ordinary brokerage account is not enough. Second, will the contribution leave enough accessible cash for expenses before the one-year maturity? A published redemption window is not equivalent to withdrawing from a bank account any day.
Third, how does the specific issue compare with alternatives you actually qualify for? Consider access, term, return basis and the legal structure of each product. A listed sukuk can be sold at a market price that may differ from face value; a bank account follows its own withdrawal and rate rules. Sah is a distinct government savings product, not a generic promise that all sukuk behave the same way.
Use the programme maximum as a cumulative limit
NDMC states a SAR 200,000 maximum per person across programme issues. It is not a fresh SAR 200,000 allowance for every monthly issue. If a hypothetical eligible saver already holds SAR 195,000 under the programme, only SAR 5,000 of headroom remains under that stated maximum, subject to the institution's current records and issue rules.
Because Sah subscriptions use SAR 1,000 nominal units, the saver in this example could consider no more than five additional units within that headroom. Check the live portal and participating institution for the actual capacity before submitting; do not infer it solely from an old account screenshot. Keep allocation confirmations from prior issues to reconcile the cumulative total.
Sources and further reading
Primary references checked for this guide. Fees, trading hours and regulatory permissions can change; confirm the current terms before acting.
Can a Saudi resident who is not a citizen subscribe to Sah?+
The NDMC currently limits Sah subscriptions to Saudi citizens older than 18. Residence alone does not meet the stated eligibility rule.
Can I buy or sell Sah on Tadawul?+
No. The NDMC says Sah is registered but not traded on the Saudi Exchange. Subscription and early redemption go through participating institutions and published windows.
Is the return the same every month?+
No. The return is fixed for a particular issue but is set according to market conditions for each issue. Check the current NDMC calendar and announcement.
Do I keep the accrued profit if I redeem early?+
No. The NDMC states that a holder who exits before maturity does not receive the accrued profit. Early redemption is available only in the windows shown by the programme calendar.
Risk warning
Sah terms, returns and windows can change between issues. Early redemption forfeits accrued profit, and the product is restricted to eligible subscribers. This is an educational description, not a personal savings recommendation or religious ruling.
Compare brokers available to Saudi residents
These are the international broker cards from our Saudi comparison. None has verified direct Tadawul access or a Saudi CMA licence in that comparison. For Saudi-listed shares, REITs and sukuk, use the official Saudi Exchange member directory and check the member's CMA permissions. Sah subscriptions use the institutions currently listed by NDMC. The broker cards below compare international investing accounts for other products; they are not Sah subscription channels.